Insurance Risk Management: Protecting Your Family's Finances
The Value of Insuring Against Life’s Risks
Did you know that…
- Nearly half of American adults do not have any life insurance coverage.¹
- Roughly two-thirds of working Americans lack long-term disability insurance.²
- More than 15% of U.S. drivers are uninsured nationwide — and in Florida, uninsured and underinsured drivers make up nearly half of all motorists on the road.³
These numbers highlight a simple truth: many families are more financially exposed than they realize.
Why Insurance Is a Core Part of Risk Management Strategies
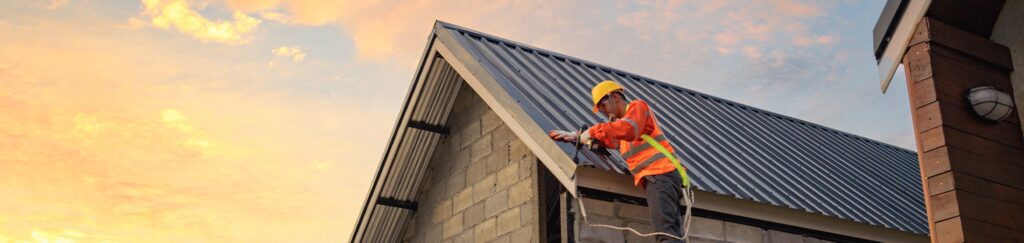
Ask a homeowner about replacing a roof, and you’ll likely hear it’s one of the least satisfying expenses they’ll ever face. The value is obvious, but it doesn’t offer the same satisfaction as new landscaping.
Yet if a heavy storm rolls through, ask that same homeowner whether they’d rather have had nice flowers or a sturdy roof.
Insurance works the same way. It’s rarely a gratifying expense, but it can protect you against the financial storms life sends your way.
Common Financial Risks Insurance Helps Protect Against
Life’s uncertainties are wide-ranging, and many of them can threaten your family’s financial security. Some of the most common risks include:
- A home damaged or destroyed by fire
- A car accident that leads to significant financial loss
- The inability to earn a living due to death or disability
That last risk deserves special attention. If something happens to you — whether through death or disability — it can create long-term financial hardship for the people who depend on you most. This is where life and disability insurance play a central role in protecting family finances.
Insurance for Financial Protection: Required vs. Optional Coverage
Some insurance, like home or auto coverage, may be legally required. Other types — like life or disability insurance — are not mandated, which can tempt people to skip them.
It’s easy to see insurance premiums as a guaranteed cost and assume the risk of a larger loss instead, simply because that loss feels less likely to happen.
But insurance premiums aren’t a financial loss. They’re a deliberate part of a sound risk management strategy — designed to protect you and your family as you build and preserve personal wealth.
Frequently Asked Questions
What is insurance risk management?
Insurance risk management is the practice of using insurance — such as life, disability, home, and auto coverage — to protect your finances against events that could otherwise cause significant financial loss.
Why do so many Americans go without life or disability insurance?
Because life and disability insurance aren’t legally required, many people are tempted to avoid the certain cost of premiums, even though it means risking a much larger, less predictable financial loss down the road.
How does disability insurance protect family finances?
Disability insurance replaces a portion of your income if you’re unable to work due to illness or injury, helping protect your family from the long-term financial impact of lost income.
Are insurance premiums really a financial loss?
No. Premiums are better understood as an investment in financial protection — they help shield the wealth you’re working to build rather than represent money lost.
Why does uninsured driver coverage matter in Florida?
Florida has one of the highest rates of uninsured and underinsured drivers in the country, which makes adequate auto insurance coverage an especially important part of a Florida resident’s overall risk management strategy.
¹ LIMRA and Life Happens, 2024 Insurance Barometer Study. ² Policygenius Disability Preparedness Survey, 2024. ³ Insurance Research Council, 2023; Insurance Information Institute, Florida uninsured/underinsured motorist estimates.
The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Federal and state laws and regulations are subject to change, which may impact after-tax investment returns. Please consult legal or tax professionals for specific information regarding your individual situation.
Several factors affect the cost and availability of life insurance, including age, health, and the type and amount of insurance purchased. Life insurance policies have expenses, including mortality and other charges. If a policy is surrendered prematurely, the policyholder may pay surrender charges and face income tax implications. You should determine whether you are insurable before implementing a strategy involving life insurance. Any guarantees associated with a policy are dependent on the ability of the issuing insurance company to continue making claim payments.
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult a legal or tax professional for specific information regarding your individual situation. The opinions expressed and material provided are for general information and should not be considered a solicitation for the purchase or sale of any security.


