

Split Annuity Strategy: Retirement Income Now and Principal Rebuilt Over Time
A split annuity strategy divides a lump sum between two annuities bought at the same time: an immediate annuity that pays income for a set number of years, and a tax deferred annuity that grows to rebuild the original principal by the end of that term. Results depend on the contracts and insurer
Key Takeaways
A split annuity strategy uses one lump sum to buy two annuities: a fixed-period immediate annuity for income and a single-premium tax deferred annuity for growth.
In the hypothetical example below, $300,000 is split into $117,852 and $182,148 over 10 years. That produces about $1,138 per month in income while the deferred annuity grows back to $300,000. This is an illustration, not a promise.
Withdrawals from the deferred annuity are taxed as ordinary income, and withdrawals before age 59½ may face a 10% federal penalty unless an exception applies.
Annuities can carry fees and surrender charges. They are not insured by the FDIC, and guarantees depend on the issuing insurer’s claims-paying ability.
When the immediate annuity’s term ends, the strategy can be repeated with the restored funds.
Table of Content
- What Is a Split Annuity Strategy?
- What Is an Annuity?
- How Does a Split Annuity Strategy Work?
- Split Annuity Strategy Example: How the Numbers Can Play Out?
- How Does a Retirement Income Annuity Fit a Split Strategy?
- How Is a Split Annuity Strategy Taxed?
- Costs, Risks, and Limits to Understand First
- Is a Split Annuity Strategy Right for You?
- Frequently Asked Questions
What Is a Split Annuity Strategy?
A split annuity strategy is a retirement income approach that uses two annuities bought at the same time with one lump sum. One annuity pays income right away. The other grows tax deferred, so by the end of the term your original principal is designed to be restored.
Market swings can make portfolio-based income feel unpredictable. In the first quarter of 2020, the S&P 500 lost nearly 20% of its value, roughly $5.6 trillion. Retirees and pre-retirees who rely on their portfolios for income felt that drop directly.
For investors who want to step away from market ups and downs, an annuity income strategy can offer more stability. Annuities are insurance contracts built for retirement purposes rather than market-tracking investments. Variable annuities are the exception, and they are covered in the risks section below.
What Is an Annuity?
An annuity is a contract between you and an insurance company. You pay the insurer a lump sum or a series of payments, and the insurer agrees to pay you back, either right away or at a future date.
Here is how an annuity works:
- You fund it with a lump sum or with regular payments.
- In exchange, the insurer agrees to make payments to you, either immediately or later.
- Money inside the contract grows on a tax-deferred basis.
- Unlike IRAs and 401(k)s, annuities have no contribution limits.
That flexibility is why annuities can be structured creatively, including as part of a split annuity strategy.
Did You Know: Annuity guarantees come from the issuing insurance company, not from the government. The contract’s strength depends on that insurer’s claims-paying ability.
How Does a Split Annuity Strategy Work?
A split annuity strategy divides one lump sum between two annuities bought on the same day. The immediate annuity pays income for a fixed number of years. The tax deferred annuity takes no withdrawals during that time and grows to rebuild your principal.
- Divide the lump sum. The split is calculated so the deferred annuity can grow back to the original amount by the end of the term.
- Buy a fixed-period immediate annuity. It starts paying income right away for a set number of years.
- Buy a single-premium tax deferred annuity. It grows in the background with no withdrawals during the term.
- Collect income while the deferred annuity grows. The goal is tax-advantaged income now and a rebuilt balance later.
- Repeat or reassess. When the term ends, the restored funds can be used to start the cycle again.
What Is an Immediate Annuity?
An immediate annuity is an insurance contract that begins paying income right away in exchange for a lump sum. In a split strategy, a fixed-period immediate annuity pays for a defined number of years. It is the income engine of the strategy.
What Is a Tax Deferred Annuity?
A tax deferred annuity is a contract that grows without being taxed each year. You owe tax only when you withdraw money. In a split strategy, a single-premium tax deferred annuity takes no withdrawals during the term, so the balance can grow back toward your original principal.
Can the Strategy Be Repeated?
Yes. Once the immediate annuity’s term ends, the strategy can be repeated using the restored funds in the deferred annuity. That creates a renewable income cycle. Any withdrawals from the deferred annuity are taxed as ordinary income.
Split Annuity Strategy Example: How the Numbers Can Play Out
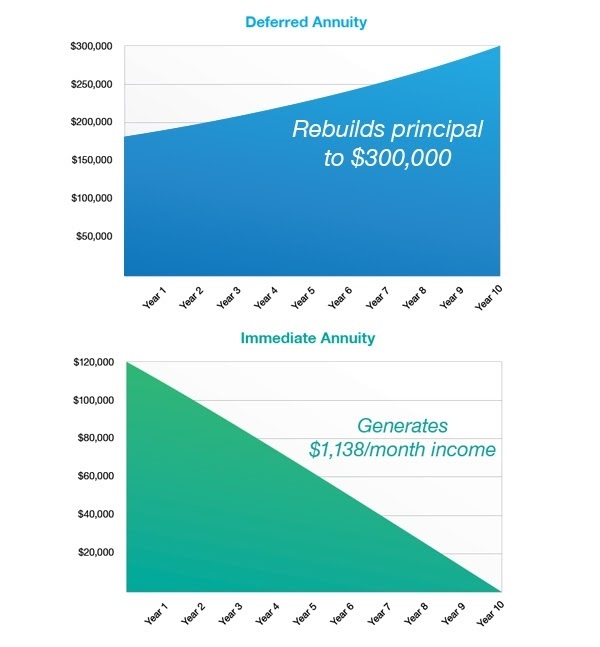
In a hypothetical example, a retiree splits $300,000 between an immediate annuity and a deferred annuity. The immediate annuity pays about $1,138 per month for 10 years. The deferred annuity grows back to $300,000 over the same period.
Hypothetical scenario:
Suppose Diane, a retiree in Fort Myers, Florida, splits $300,000 between two annuities as shown below.
| Annuity Type | Amount Invested | Term | Hypothetical Return |
|---|---|---|---|
| Deferred Annuity | $182,148 | 10 years | 5% |
| Immediate Annuity | $117,852 | 10 years | 3% |
Projected results over 10 years:
- The immediate annuity is projected to pay about $1,138 per month, or about $136,560 in total.
- The deferred annuity is projected to grow back to $300,000, replacing Diane’s original principal in full. This assumes monthly compounding.
This example is hypothetical and for illustration only. Actual results vary based on the annuity contract, the insurer, and market conditions. It does not represent any client’s results.
Common Mistake: Treating illustrated rates as guaranteed. Always compare the guaranteed rate in the contract with any projected rate in a sales illustration.
How Does a Retirement Income Annuity Fit a Split Strategy?
A retirement income annuity is an annuity used to turn savings into regular payments. In a split annuity strategy, the immediate annuity plays that role, while the tax deferred annuity works to rebuild the principal that funded it.
Annuities for retirement come in several forms. Both of the types below can play a role in a split strategy, but they serve different purposes.
| Feature | Fixed (Immediate) Annuity | Tax Deferred Annuity |
|---|---|---|
| Role in the strategy | Pays retirement income | Rebuilds principal |
| When payments start | Right away, for a defined period | No withdrawals during the term |
| How money is treated | Converted into an income stream | Grows without yearly taxation |
| Tax when money comes out | Income payments are taxable under IRS annuity rules [VERIFY: IRS Publication 575] | Withdrawals taxed as ordinary income |
Pro Tip: Ask the insurer for the contract’s surrender schedule and guaranteed rates in writing before you compare options. Those two details often matter more than the headline rate.
How Is a Split Annuity Strategy Taxed?
Withdrawals from the deferred annuity are taxed as ordinary income. Growth inside the contract is tax deferred until you take money out. Withdrawals before age 59½ may also face a 10% federal tax penalty unless an exception applies.
- If you fund the annuities with after-tax money, part of each immediate annuity payment is generally treated as a return of your own principal and part is taxable.
- If you fund them with IRA or 401(k) money, different tax rules can apply, so confirm the details with a tax professional.
- Florida does not levy a state personal income tax, so federal rules drive most of the tax picture for Florida residents.
Costs, Risks, and Limits to Understand First
Annuities can offer stability, but they come with fees, surrender charges, and tax rules. Review each contract’s terms before committing funds, because the limits are part of the real cost of the strategy.
- Fees may include account and administrative fees, investment management fees, mortality and expense charges, and fees for optional benefits.
- Surrender charges typically apply and are usually highest in the early years of the contract.
- Taxes: withdrawals and income payments are taxed as ordinary income, and withdrawals before age 59½ may face a 10% federal penalty unless an exception applies.
- No government insurance: annuities are not guaranteed by the FDIC or any other government agency. Guarantees are backed by the claims-paying ability of the issuing insurance company.
- Variable annuities carry investment risk. Return and principal value fluctuate with the market and are not guaranteed. They are sold by prospectus, which describes investment objectives, risks, charges, and expenses and should be read carefully.
| Potential Advantages | Potential Drawbacks |
|---|---|
| Income begins right away for a set period | Surrender charges and fees can reduce results |
| Deferred annuity grows without yearly taxation | Withdrawals are taxed as ordinary income |
| Designed to restore the original principal | Restoring principal is not guaranteed and depends on the contract and insurer |
| Can be repeated once the term ends | Not insured by the FDIC or any government agency |
Is a Split Annuity Strategy Right for You?
A split annuity strategy is not the right fit for everyone. Every retirement plan is different, so the strategy should be weighed against your income needs, your other assets, your taxes, and your comfort with contract limits.
If you are a Florida retiree exploring annuity retirement income options, or you want to see how a split annuity strategy could sit alongside your other assets, start with your full financial picture. That includes your broader retirement income planning page, retirement income planning approach and your tax planning page, tax planning considerations.
Tyler Harrelson, CLTC®, CES®, CFS®, and the team at The Art and Science of Successful Planning (ASOFSP) in Fort Myers, Florida, work with individuals and families across Florida to evaluate whether strategies like this align with their broader retirement goals. If you would like to talk it through, you are welcome.
Frequently Asked Questions
What is an annuity and how does it work?
An annuity is a contract between you and an insurance company. You fund it with a lump sum or regular payments, and the insurer agrees to pay you back, either right away or at a future date. Money inside the contract grows tax deferred. Unlike IRAs and 401(k)s, annuities have no contribution limits.
What is an immediate annuity?
An immediate annuity is an insurance contract that begins paying income right away in exchange for a lump sum. In a split annuity strategy, a fixed-period immediate annuity pays you income for a set number of years, while a second, tax deferred annuity grows in the background. The payments are taxed under federal annuity rules.
How does a tax deferred annuity work?
A tax deferred annuity grows without being taxed each year. You owe tax only when you take money out, and withdrawals are taxed as ordinary income. Withdrawals before age 59½ may also face a 10% federal tax penalty unless an exception applies. In a split strategy, this annuity takes no withdrawals during the term so the balance can grow.
Can annuities for retirement provide steady income?
Yes, some annuities can. Annuities are insurance contracts designed for retirement, and an immediate annuity pays income on a set schedule for a defined period. Payments are backed by the issuing insurer's claims-paying ability, not by the government, and fees, surrender charges, and taxes can affect the net result.
Does a split annuity strategy guarantee my principal comes back?
No. The strategy is designed to rebuild your principal through growth in the deferred annuity, but results vary by contract, insurer, and rates. Annuities are not FDIC insured, and guarantees rely on the issuing insurer's claims-paying ability. Surrender charges and fees can also affect outcomes, so review the contract terms before committing funds.
What happens when the immediate annuity term ends?
The immediate annuity's payments stop at the end of its fixed term. By then, the deferred annuity is designed to have grown back to the original amount. You can then repeat the strategy with those restored funds, creating a renewable income cycle, or choose a different approach. Withdrawals from the deferred annuity are taxed as ordinary income.


